Sent Money to Wrong UPI ID or Account? Recover 100% Legally (2026)
sent money to wrong upi id recipient refusing to return legal notice, how to recover money sent to wrong bank account in india, section 72 contract act mistaken payment recovery, section 314 bns dishonest misappropriation of wrong upi transfer, npci upi dispute chargeback wrong transfer, can bank freeze recipient account for mistaken upi transfer
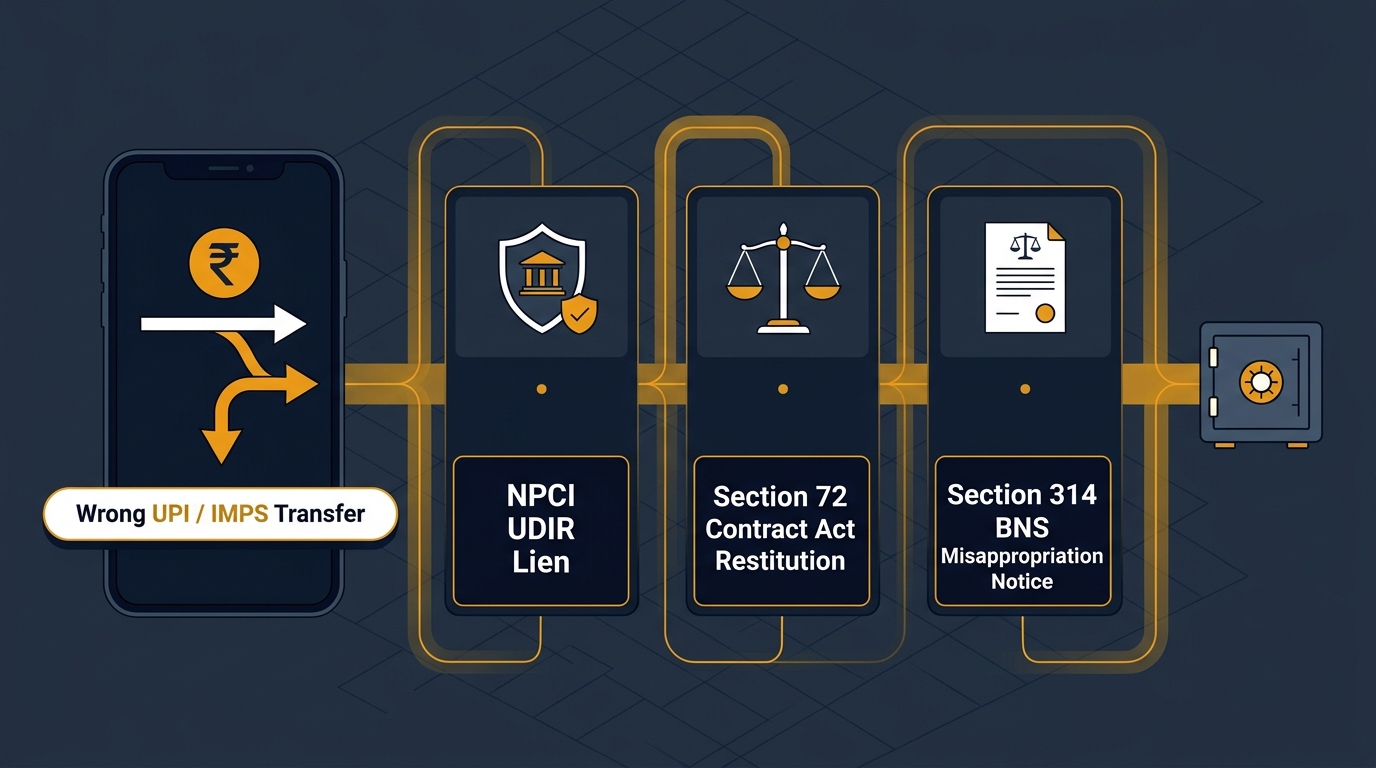
Table of Contents
Table of Contents
Swipe →You enter one wrong digit in a mobile number or bank account, confirm your UPI PIN, and press send. Two seconds later, your Rs 25,000 or Rs 1,50,000 sits in a stranger's bank account. You call the number or send a polite text, and the receiver blocks you or claims they already spent the money.
Most callers hear the same scripted line from customer care: a completed UPI or NEFT transfer cannot be cancelled. That half-truth makes thousands of Indians give up on hard-earned savings every week. While your bank cannot press a magic undo button, Indian law gives the recipient zero right to keep your money.
Keeping cash credited by mistake triggers both civil restitution under Section 72 of the Indian Contract Act, 1872 and criminal prosecution under Section 314 of the Bharatiya Nyaya Sanhita (BNS), 2023. This guide explains the exact two-stage banking and legal playbook to lock the funds, trace the recipient, and recover every rupee in 2026.
1. Why Banks Cannot Auto-Debit Wrong UPI Transfers
RBI STP Rules and Supreme Court Privacy Limits
Electronic banking in India runs on Straight-Through Processing. Under RBI Circular RBI/2010-11/235 (DPSS (CO) EPPD No. 863/04.03.01/2010-11), NEFT, RTGS, and IMPS credits rely strictly on the destination account number you type. Banks do not match account names automatically during settlement unless you use the pre-transfer verification tool.
Once money clears into the receiver's account, the destination bank cannot pull it back on your verbal request. In Jammu & Kashmir Bank Ltd. v. Attar-Ul-Nissa (1966) and State Bank of India v. Metro Exporters (P) Ltd. (AIR 2014 SC 3206), the Supreme Court ruled that a bank cannot unilaterally reverse customer credits without explicit consent or a valid court order. That banking safeguard protects innocent depositors, yet it also slows down reversals when strangers act in bad faith.
To prevent typing errors, the RBI mandated a free Beneficiary Account Name Look-up facility for RTGS and NEFT by April 1, 2025, matching the name check already shown on UPI and IMPS screens. If a bank interface failed to show the true CBS payee name despite you using the look-up tool, preserve screenshots immediately for an Ombudsman claim.
Wrong Transfer vs Failed UPI vs Cyber Fraud
Many users cite the wrong RBI rule and lose weeks waiting for bank penalties that do not apply. Know which legal bucket covers your loss before filing any ticket:
- Erroneous Customer Transfer (This Guide): You entered the wrong UPI ID, mobile number, or account digits and typed your PIN. Zero liability rules do not cover your typo, so recovery runs through NPCI UDIR consent recall, Section 72 restitution, and Section 314 BNS pressure.
- Failed Technical Transaction: Your account got debited due to a server timeout, and the receiver never got the credit. Here, banks must auto-reverse within T+1 or T+5 days or pay Rs 100 daily under our guide on failed UPI transaction RBI TAT rules and compensation.
- Unauthorised Phishing Fraud: Scammers drained your bank account without your valid authorization or via remote access malware. That falls under RBI's 3-day reporting protection covered in our wrong UPI transfer money recovery process hub.
2. Stage 1: First 48 Hours UDIR Chargeback and Bank Lien
Lodge an NPCI UDIR Dispute With Your 12-Digit UTR
Speed decides whether the mistaken money stays in the receiver's bank balance or gets withdrawn via ATM and spent. Execute these four actions within the first two to six hours of the error:
- Save the 12-Digit UTR or RRN: Download the PDF receipt or screenshot from Google Pay, PhonePe, Paytm, BHIM, or net banking showing the exact 12-digit UTR number, timestamp, source VPA, and wrong destination account.
- Open an In-App UPI Dispute: Tap the transaction inside your payment app, select Report an Issue, and pick Wrong Beneficiary or Incorrectly Transferred to Another Account so a ticket enters the NPCI Unified Dispute and Issue Resolution (UDIR) queue.
- Submit the NPCI Web Form: Log the same UTR on NPCI's official UPI Dispute Redressal page under the category Incorrectly transferred to another account and save your complaint reference number.
- Save Proof of Your Intended Payee: Keep screenshots of the real invoice, vendor chat, or correct contact number showing the one-digit typo. This evidence destroys any false claim later that you paid an old debt.
Written Branch Recall Request and Consumer Precedent
Never rely only on toll-free call centres or app chat bots. Visit your home bank branch (or email your bank's Grievance Officer) the same day with a signed recall letter. You can adapt our wrong account transfer refund application format to hand in at the desk and collect a stamped receipt.
Ask your branch manager to immediately trigger an inter-bank recall and temporary lien request to the beneficiary bank branch. If both accounts sit in the same bank, the home branch can phone the recipient and verify consent the same afternoon.
Written proof creates legal liability for slow bank staff. In Ramesh Chand v. State Bank of India & Punjab National Bank (District Consumer Commission, Rohtak, 2022), the complainant reported a wrong Rs 78,500 transfer within two hours. Because PNB waited 14 days to notify the recipient while the money was withdrawn, the Consumer Court held both banks jointly liable for deficiency in service and ordered a full Rs 78,500 refund with 9% interest, Rs 15,000 damages, and Rs 5,000 costs.
3. Stage 2: Section 72 Contract Act and Section 314 BNS
Civil Restitution Duty Under Section 72 Contract Act
When the beneficiary bank calls the recipient and the recipient refuses consent, banking tools hit a wall. That refusal shifts your case from bank customer care to enforceable Indian statutory law.
Section 72 of the Indian Contract Act, 1872 states in plain words: A person to whom money has been paid, or anything delivered, by mistake or under coercion, must repay or return it. Under this rule, a stranger who gets Rs 85,000 in their savings account by error gains zero ownership title.
In Sales Tax Officer, Banaras v. Kanhaiya Lal Mukundlal Saraf (AIR 1959 SC 135), a five-judge Constitution Bench of the Supreme Court held that Section 72 applies fully to mistakes of fact. Later, in Mahabir Kishore & Ors. v. State of Madhya Pradesh ((1989) 4 SCC 1), the Supreme Court affirmed that retaining mistaken money violates the doctrine against unjust enrichment. Furthermore, the Karnataka High Court in S. Kotrabasappa v. Indian Bank (1987) confirmed that anyone who uses money credited by mistake owes full restitution plus statutory interest under Section 73.
Criminal Misappropriation Under Section 314 BNS 2023
Accidental receipt at the first minute is not a crime. However, criminal liability begins the moment the recipient learns of the error and refuses to return the money, blocks your number, or withdraws the balance.
Under Section 314 of the Bharatiya Nyaya Sanhita (BNS), 2023 (which replaced Section 403 of the Indian Penal Code, 1860), dishonestly misappropriating or converting movable property to your own use is a criminal offense punishable with up to two years imprisonment, a fine, or both. In repeated High Court quashing petitions, judges have clarified that once written notice puts a recipient on clear knowledge that a bank credit belongs to someone else, spending that cash proves dishonest intent (mens rea).
The table below compares your real financial recovery across four escalation stages on an illustrative Rs 85,000 mistaken UPI or IMPS transfer.
| Recovery Stage | Trigger Condition | Principal Claim | Added Interest or Damages | Typical Payout Window |
|---|---|---|---|---|
| 1. UDIR + Branch Recall | Recipient signs bank debit consent | Rs 85,000 | Rs 0 (Fee-free reversal) | 3 to 10 working days |
| 2. Advocate Legal Notice | Receiver ignores bank or blocks calls | Rs 85,000 | 12% to 18% p.a. interest + notice cost | 7 to 15 days |
| 3. RBI Ombudsman / Consumer Forum | Bank delayed lien past 30 days | Rs 85,000 | 9% interest + Rs 15,000 to Rs 25,000 costs | 45 days to 6 months |
| 4. Lok Adalat / Civil Suit | Recipient spent cash and refused notice | Rs 85,000 | 12% pendente lite interest + court costs | 2 to 8 months |
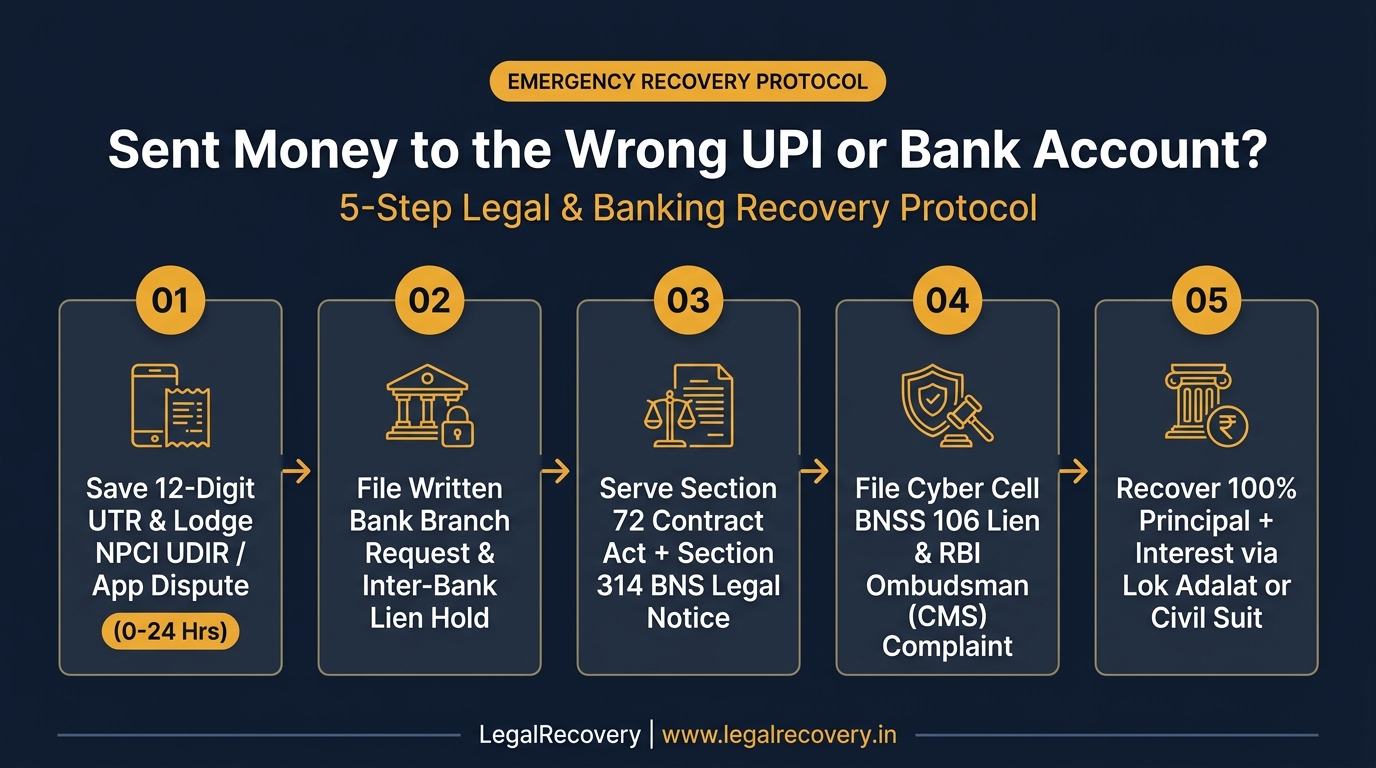
Visual Dispute Resolution & Recovery Framework
4. How to Trace Recipient KYC and Freeze Withdrawn Cash
Overcoming Bank Customer Privacy Excuses
Every victim hits one roadblock: your bank refuses to give you the stranger's home address, citing RBI customer privacy norms. You do not need to wait helplessly behind a privacy wall. Use these four lawful methods to serve notice or trace KYC details:
- Check UPI Phone Handles and VPA Data: When you pay a wrong mobile number on GPay or PhonePe, you already hold the recipient's active phone number and registered banking name. Under Supreme Court electronic service norms, an advocate notice delivered via WhatsApp and SMS counts as valid notice of mistake under Section 314 BNS.
- Inter-Bank Nodal Service Protocol: Send an advocate legal notice to your bank's Principal Nodal Officer and the beneficiary bank's Nodal Officer, quoting the 12-digit UTR. Demand that the beneficiary bank forward your enclosed demand notice directly to the recipient's KYC email and address on record and place a disputed-sum hold.
- Police Inquiry Under Section 314 BNS: Privacy rules between banks do not shield a suspect from a lawful police investigation. Once an Investigating Officer takes cognizance of a Section 314 BNS dishonest misappropriation complaint, the beneficiary bank must disclose full Aadhaar, PAN, and address KYC under Section 94 of the BNSS, 2023 (replacing Section 91 CrPC).
- Civil Court Discovery Order: If you file a civil recovery suit naming John Doe or the destination bank as a pro-forma defendant, the Civil Judge can direct the bank to produce the account holder's verified address for summons service.
Using Section 106 BNSS to Mark a Lien on Funds
If the wrong recipient turns hostile or starts draining the account via UPI or ATM withdrawals, submit an urgent complaint on the National Cyber Crime Reporting Portal or at your local police station citing Section 314 BNS. Request the officer to issue a bank requisition under Section 106 of the Bharatiya Nagarik Suraksha Sanhita (BNSS), 2023 (formerly Section 102 CrPC).
A Section 106 BNSS direction lets police instruct the beneficiary bank to freeze or mark a surgical lien over the exact disputed sum (for example, Rs 85,000). Remember that courts and NCDRC orders treat full-account freezes as excessive when a targeted lien protects the claim; review our guide on bank account lien or cyber freeze legal remedies to understand how banks process lien holds versus total debit freezes.
Once a lien freezes Rs 85,000 inside the stranger's salary or business account, their incentive reverses overnight. They cannot clear that lien without signing a bank refund consent letter or obtaining a Magistrate No-Objection Order after returning your money.
5. RBI Integrated Ombudsman and Consumer Court Remedies
The 30-Day Rule Under RB-IOS 2021
Banks often stall wrong-transfer victims by bouncing tickets between the remitter bank and the beneficiary bank. Under the Reserve Bank - Integrated Ombudsman Scheme (RB-IOS), 2021, both regulated banks owe you timely facilitation and transparent status updates.
Wait exactly 30 calendar days from your written branch or Nodal Officer complaint. If both banks fail to reply, refuse to prove they contacted the recipient, or sit on your inter-bank recall request while funds get withdrawn, lodge a free complaint on cms.rbi.org.in. Follow our RBI Ombudsman complaint escalation guide for exact filing fields and Clause 10 grounds.
Be realistic about Ombudsman limits: if the stranger spent the cash ten minutes after your transfer before you even notified the bank, the RBI Ombudsman cannot force the bank to pay out of pocket. However, where the bank delayed raising the UDIR recall or missed marking a timely hold while funds sat intact, Ombudsman awards and District Consumer Commissions hold the bank liable for deficiency in service under Section 2(11) of the Consumer Protection Act, 2019.
Forum Comparison Matrix for Wrong Transfers
Choose the right legal track based on your transaction size and whether the recipient still holds the funds. Compare every 2026 forum below.
| Legal or Banking Forum | Best Used When | Filing Fee (2026) | Average Timeline | Legal Power and Outcome |
|---|---|---|---|---|
| NPCI UDIR + Branch Letter | First 48 hours after wrong transfer | Free (Rs 0) | 3 to 10 days | Seeks recipient debit consent and logs bank timestamp |
| Advocate Legal Notice | Recipient refuses, blocks, or stalls | Fixed low fee | 7 to 15 days | Proves mens rea u/s 314 BNS and locks 18% interest |
| Police / Cyber Cell (Sec 314 BNS) | Recipient withdraws funds or stays silent | Free (Rs 0) | 3 to 21 days for lien | Triggers Section 106 BNSS lien and KYC tracing |
| RBI Ombudsman (CMS Portal) | Bank failed to act within 30 days | Free (Rs 0) | 30 to 90 days | Penalizes bank deficiency and forces escalation |
| Permanent Lok Adalat / Civil Suit | Written notice expired unpaid | Rs 0 (PLA) / State fee | 2 to 8 months | Binding executable decree and asset attachment |
6. Section 63 BSA Evidence Bundle and Lok Adalat Suit
Six Digital Records Required Under Section 63 BSA
Whether you file a police complaint, an RBI Ombudsman claim, or a civil recovery petition, digital proof must satisfy Section 63 of the Bharatiya Sakshya Adhiniyam (BSA), 2023 (which replaced Section 65B of the old Evidence Act). Assemble these six files in one PDF folder:
- Certified Bank Statement PDF: Export the official bank statement showing the debit entry, 12-digit UTR or IMPS reference, and date.
- UPI App Receipt Screenshot: Capture the screen showing the wrong VPA, masked payee name, and your submitted UDIR dispute number.
- Branch Recall and Nodal Emails: Keep your stamped branch letter and every email sent to your bank and the receiver's bank Nodal Officer.
- Recipient Refusal or Block Proof: Screenshot your polite request message, double-blue ticks, refusal replies, or blocked profile icon. Learn how courts verify WhatsApp and digital UTR proof under Section 63 BSA.
- Intended Payee Proof: Attach the genuine invoice, WhatsApp chat, or bank passbook entry of the person you actually meant to pay, proving an honest mistake.
- Signed Section 63 BSA Certificate: Attach a standard electronic record certificate signed by you detailing the smartphone or laptop used to export the files.
Permanent Lok Adalat and Section 72 Civil Recovery
If an individual ignores your formal legal notice, you do not need to wait five years in a regular trial. Three faster statutory routes enforce recovery in India:
First, where your bank or the receiver's bank delayed an inter-bank recall or failed in its public utility banking duty up to Rs 1 crore, approach the Permanent Lok Adalat under Section 22C of the Legal Services Authorities Act, 1987. Filing costs zero court fee, and if conciliation fails, the Permanent Lok Adalat decides the banking dispute on merits. Second, against an identified private recipient, you can file a Pre-Litigation Lok Adalat application under Sections 19 to 21 of the same Act with zero court fee. Under the Supreme Court ruling in State of Punjab v. Jalour Singh ((2008) 2 SCC 660), any signed Lok Adalat award operates as a final, non-appealable Civil Court decree. Read our Pre-Litigation Lok Adalat money recovery guide for filing steps.
Third, file a civil recovery suit under Section 72 of the Contract Act within three years from discovering the mistake under Section 17(1)(c) read with Article 24 and Article 113 of the Limitation Act, 1963. Where the recipient admits the mistake in writing or via WhatsApp while stalling repayment, you can pursue an expedited Order 37 CPC summary suit. Under Section 2(c) of the Interest Act, 1978, serving a written demand notice entitles you to claim 12% to 18% annual interest from the notice date until recovery.
7. Section 72 and Section 314 BNS Legal Notice Format
Why an Advocate Notice Works Faster Than Personal Calls
Strangers keep mistaken transfers because they assume you do not know the law or will drop a small claim. Personal begging on WhatsApp often triggers blocking. Everything changes when they receive a formal legal notice for money recovery in India on an advocate letterhead citing exact criminal sections, Supreme Court restitution law, and bank lien tracking.
Ready to force immediate action today? You can send a Section 72 Contract Act and Section 314 BNS recovery notice drafted by an advocate and dispatched via Speed Post, WhatsApp, and Email with Nodal Bank copying.
Ready-to-Use Statutory Legal Notice Clause
Use or adapt this statutory demand clause when serving a notice on an uncooperative recipient and copying the beneficiary bank Nodal Officer:
STATUTORY LEGAL NOTICE U/S 72 INDIAN CONTRACT ACT, 1872 & SEC 314 BNS, 2023
To: [Recipient Name / Account Holder of Bank A/c or UPI ID], [Mobile Number / Known Address].
Copy To: The Principal Nodal Officer, [Beneficiary Bank Name] (with Reference UTR No. [12-Digit UTR]).
Date: [Insert Date]
Sir / Madam,
Under instructions from our Client, [Your Full Name], residing at [Your Address], we serve this formal notice:
1. On [Transaction Date] at [Time], our Client inadvertently transferred Rs [Amount] via [UPI / IMPS / NEFT] bearing UTR No. [12-Digit UTR] into your [UPI ID / Bank Account] due to a clerical error while paying [Intended Payee Name].
2. Our Client immediately notified [Remitter Bank] via complaint [Ticket Number] and contacted you on [Date] requesting return of the mistaken credit.
3. Despite clear knowledge of the error, you have refused debit consent and withheld the funds. Under Section 72 of the Indian Contract Act, 1872 and the Supreme Court ruling in Mahabir Kishore v. State of MP ((1989) 4 SCC 1), you hold zero legal title to money paid by mistake and are bound to restore it.
4. Retaining or spending these funds after receipt of this notice constitutes Dishonest Misappropriation of Property under Section 314 of the Bharatiya Nyaya Sanhita (BNS), 2023, carrying up to two years imprisonment and fine, alongside account lien under Section 106 BNSS.
YOU ARE CALLED UPON to refund Rs [Amount] to our Client's account [Bank Account / UPI ID] or sign bank debit reversal consent within SEVEN (7) DAYS, failing which our Client will file a criminal complaint u/s 314 BNS, a bank lien request u/s 106 BNSS, and a civil restitution suit claiming 18% annual interest and full legal costs.
Do not write off money lost to a wrong UPI number or bank account typo. Lock your 12-digit UTR trail within hours, lodge a stamped branch recall request, and serve a Section 72 Contract Act and Section 314 BNS advocate notice to recover 100% of your funds.
Popular Searches & Related Topics

Legal Recovery is India's trusted consumer protection and legal tech platform. We specialize in holding corporations accountable for unfair trade practices, deceptive marketing, and commercial fraud. With over 15,000 customers counselled, our mission is to provide fast, out-of-court resolutions by connecting you with top-tier panel advocates for immediate legal action.
Client Reviews
"I accidentally sent Rs 72,000 via UPI to an old mobile number reassigned to a stranger in Pune. The person blocked my calls after reading my WhatsApp message. LegalRecovery served a formal Section 72 Contract Act and Section 314 BNS notice via WhatsApp and bank nodal escalation. The recipient refunded the entire Rs 72,000 within six days."
Rohan Kulkarni
"A single typo in an IMPS account number sent Rs 1,45,000 of vendor stock payment to an unknown account in Chennai. My bank branch refused to share the receiver's details citing privacy. Team LegalRecovery filed a formal Nodal Officer request alongside a legal notice warning of police lien under Section 106 BNSS. The receiver signed bank debit consent in ten days."
Meenakshi Iyer
"My PhonePe transfer of Rs 38,500 went to the wrong VPA while paying hospital fees. Support closed my chat ticket in two days saying the transaction was successful. LegalRecovery guided my written bank recall application and drafted an advocate notice on the recipient's linked number. I got every rupee back without stepping into a court."
Aditya Sharma
"Both my remitter bank and the receiver's bank delayed acting on my wrong NEFT complaint for three weeks while Rs 95,000 sat untouched. LegalRecovery drafted a formal RBI Ombudsman escalation and bank deficiency notice citing Consumer Commission precedents. The beneficiary bank marked a hold immediately and cleared the reversal."
Farhan Siddiqui
"I mistakenly transferred Rs 54,000 twice to a former supplier who later denied receiving extra money and blocked me. LegalRecovery compiled my UTR logs with a Section 63 BSA certificate and served a seven-day demand notice. Facing a Permanent Lok Adalat claim plus 18% interest, the party returned the full Rs 54,000."
Kavita Nair
Frequently Asked Questions
Related Articles
Contractor Holding Retention Money or RA Bills? Recover Now (2026)
subcontractor retention money recovery legal notice india, pay when paid clause validity in india, back to back payment clause subcontractor recovery, contractor not releasing retention money defect liability period, section 24 msmed act overriding effect pay when paid, commercial dispute running account bills recovery
Read Article
How to Recover Money Lent to a Friend via UPI or GPay (2026)
recover money from friend sent via upi without agreement, how to recover money from friend legally in india, gpay transaction proof for money recovery case, section 63 bharatiya sakshya adhiniyam whatsapp evidence, legal notice to friend for money recovery, friendly loan recovery without promissory note, section 70 indian contract act non gratuitous transfer, upi utr number evidence civil recovery, order 37 cpc summary suit friendly loan, admissions trap legal notice strategy, section 18 limitation act acknowledgment of debt
Read Article
E-Commerce App Forcing Wallet Refund Over Bank Account? Legal Fix
ecommerce forcing wallet refund instead of original payment method, can company force store credit instead of bank refund india, myntra ajio refund stuck in wallet transfer to bank, ccpa guidelines against forced wallet refunds dark patterns, rbi prepaid payment instrument wallet refund to source, legal notice for original source refund ecommerce, section 2 47 consumer protection act unfair trade practice, dark patterns forced action interface interference, closed loop wallet refund bank withdrawal, e daakhil complaint for store credit refund
Read Article
Ex-Flatmate Left Without Paying Rent or Deposit? Legal Recovery
recover rent and security deposit from flatmate india, flatmate not returning security deposit share, roommate left without paying rent legal notice, splitwise proof in legal notice money recovery, joint tenancy contribution recovery india, how to recover money from roommate legally, section 69 contract act rent reimbursement, section 43 contract act contribution, section 72 unjust enrichment flatmate deposit, section 316 bns criminal breach of trust tenant deposit, lead tenant pocketed deposit refund legal action, order 38 rule 5 bank attachment flatmate debt
Read ArticleAbout Author
Anuj Anand Malik
View ProfileAnuj Anand Malik, Founder of AMA Legal Solutions, is a trusted advocate, loan settlement expert, legal advisor, and banking lawyer. With over a decade of experience in loan settlement, corporate law, financial disputes, and compliance, he leads a result-driven law firm based in India that helps individuals, startups, and businesses achieve legal and financial stability.
Connect on LinkedInNeed Legal Help?
Get expert advice on loan settlement, banking disputes and debt relief.
Start Recovery NowRequest Callback